Central Banks Bought 79 Tonnes of Gold in August, Goldman Says
Central banks bought 79 tonnes of gold in August, four times the pre-2022 average, Goldman Sachs estimates. The Dutch and French quietly pulled reserves from New York as storage disclosure fell.
By Olivia Hart
4 min read
Updated
What's News
- Goldman Sachs estimated central banks bought 79 tonnes of gold in August 2026, more than four times the pre-2022 monthly average of 17 tonnes.
- China accounted for roughly 25 tonnes of August demand, the largest identifiable buyer, on a seasonally adjusted three-month pace of 85 tonnes a month.
- De Nederlandsche Bank reallocated 86 tons of gold from the New York Fed and Ottawa to the Bank of England in London, citing 'increasing geopolitical unrest.'
- The Banque de France sold 129 tons (5% of its gold) from New York in March 2026, citing a purity threshold of 99.99% rather than geopolitics.
- 12% of central banks declined to disclose gold storage locations in 2026, up from 10% the prior year, and 18% declined to say where they would store gold over the next 12 months.
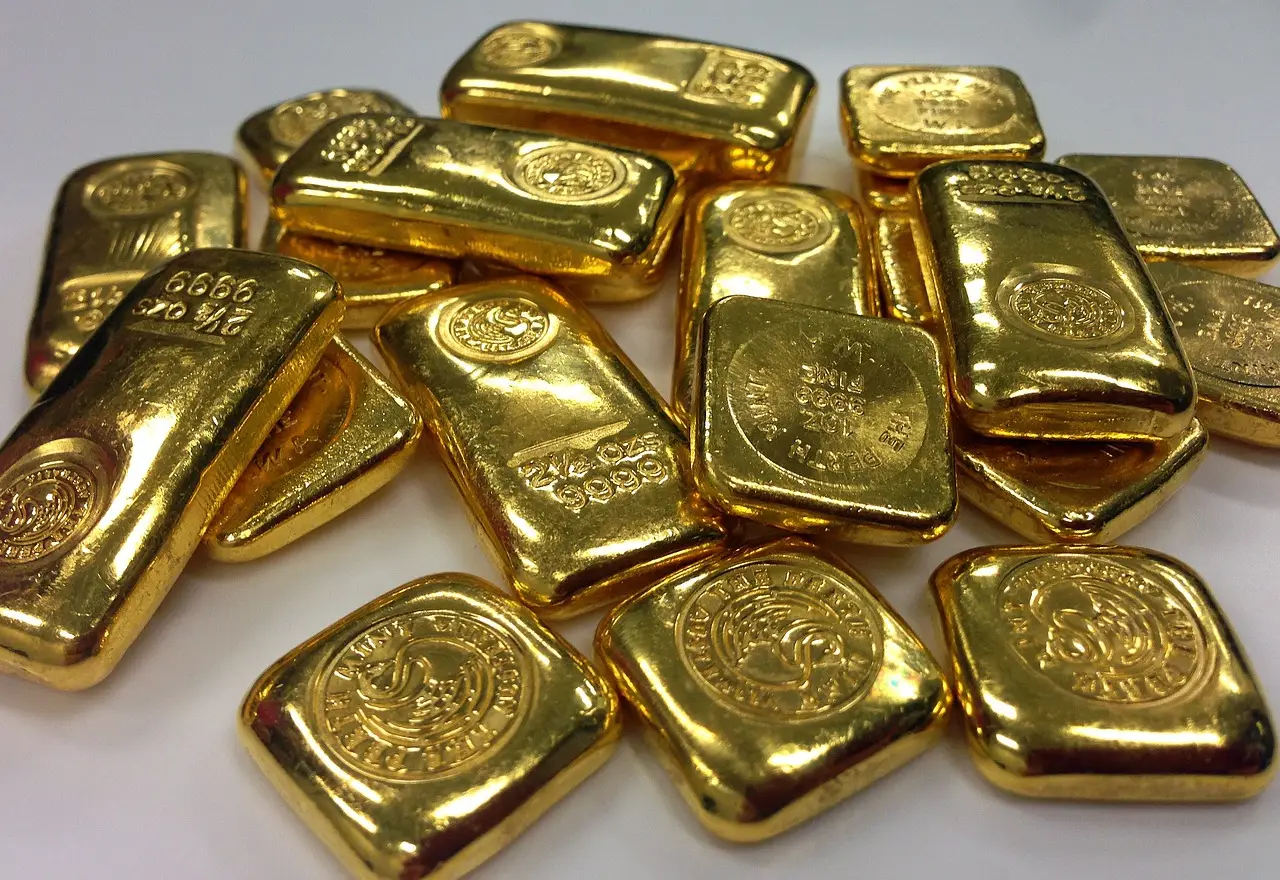
Central banks purchased 79 tonnes of gold in August, more than four times the pre-2022 monthly average of 17 tonnes, according to a Goldman Sachs note published this week.
The three-month seasonally adjusted pace is now 85 tonnes a month, Goldman said. China accounted for roughly 25 tonnes of August demand, the bank estimated, making the People's Bank of China the largest identifiable buyer. The rest is opaque, a caveat that matters: unidentified buyers could easily exceed China's disclosed footprint.
Goldman pushed back on alarmist readings, noting that the People's Bank of China is "underweight in gold relative to plausible long-term allocations" and that other emerging markets are not buying at an unusually fast clip either. The structural driver, in Goldman's view, is the desire to diversify away from G7 reserve currencies, most notably the U.S. dollar—a motivation "likely to remain in place."
The four-year buying spree has largely skipped the domestic-market central banks of the U.S., Europe, and other reserve issuers. Goldman said those institutions already hold substantial gold stocks for historical reasons and have "largely been on the sidelines." Bottom line: the official-sector bid is real, but it is not yet a stampede.
Where is the gold physically moving?
For central banks that already hold large gold stocks, the question has shifted from how much to hold to where to keep it. In September, De Nederlandsche Bank confirmed it had spent the previous six months moving 86 tons of gold out of the New York Fed and Ottawa to the Bank of England in London. The Dutch central bank framed the reallocation as preparation for "serious crises" and a response to "increasing geopolitical unrest."
"Gold stored in London at the Bank of England … is considered the most easily tradable gold in the world," DNB stated. "This makes it the fastest way for DNB to deploy in a crisis situation. The part of the gold stock located in New York and Ottawa is less directly deployable."
The Banque de France took a different tack. In March, the French central bank disclosed it had sold 129 tons—5% of its total gold—from its New York stockpile and bought the equivalent in Europe. Crucially, the French made no reference to geopolitics, citing instead a need to lift the purity of its holdings above 99.99%, a threshold the U.S. stock failed to meet.
The divergences warrant skepticism. The Dutch explicitly invoked geopolitics; the French did not. Both, however, reduced U.S.-vault exposure, and the French rationale, taken at face value, is technical. Bottom line: when two G7 central banks quietly shrink their New York exposure in the same year, the pattern is the story, not the rationale.
How much secrecy is there now?
Aggregate flows confirm the picture. Central bank gold holdings at the New York Fed fell 40 tonnes in August, Goldman noted, while holdings at the Bank of England rose 46 tonnes. The shift is small in dollar terms but unmistakable in direction.
Opacity is also growing. When Goldman surveyed central banks in August about where they store their reserves, 12% declined to confirm the location, up from 10% a year earlier. The share that diversified overseas storage rose to 10% in 2026 from 2% the year before. The share that increased domestic storage climbed to 9% from 5%. Looking 12 months out, 18% of central banks declined to say where they would keep their gold, and 9% said they planned to diversify further.
The 18% refusal rate is the cleanest proxy for cross-border trust in Goldman's data. The trend is set to continue, in Goldman's framing, as reserve managers in 2026 show "broader concerns around reserve security and cross-country trust." Bottom line: the share of reserve managers who refuse to disclose is climbing faster than the share who actually move metal.
What does the data actually say?
Central banks are no longer debating how much gold to hold. They are debating where, and increasingly, with whom. The flow of metal out of U.S. vaults and the rising share of central banks that will not disclose their storage plans point to the same slow erosion of trust in dollar-based reserve infrastructure. The pace of disclosure, not just the tonnage, is the metric to watch over the next 12 months.
Original: banque-france.fr
More from Olivia Hart
Show full bio
Staff writer covering people, launches and day-to-day practice in entrepreneurship, startups and venture funding at Business Bearings.
1,072 articles