SpaceX's $1.77 Trillion IPO Redrew the Map for Advisors
SpaceX raised $75 billion at a $1.77 trillion valuation in June. ABS Global's Jon Feinberg explains why the real returns now form years before companies ever list.
By Daniel Okafor
4 min read
What's News
- SpaceX went public in June at a $1.77 trillion valuation, raising $75 billion.
- Cerebras completed a $6.4 billion IPO at a $40.6 billion valuation after being worth $8 billion two rounds earlier.
- The average U.S. company now reaches IPO more than 11 years after founding, versus 7.3 years in the late 1990s.
- Private secondary share transactions grew from $26 billion in 2013 to $226 billion in 2025.
- Anthropic raised $65 billion in Q2 2026 at a $965 billion post-money valuation and reportedly targets a $2-3 trillion IPO.
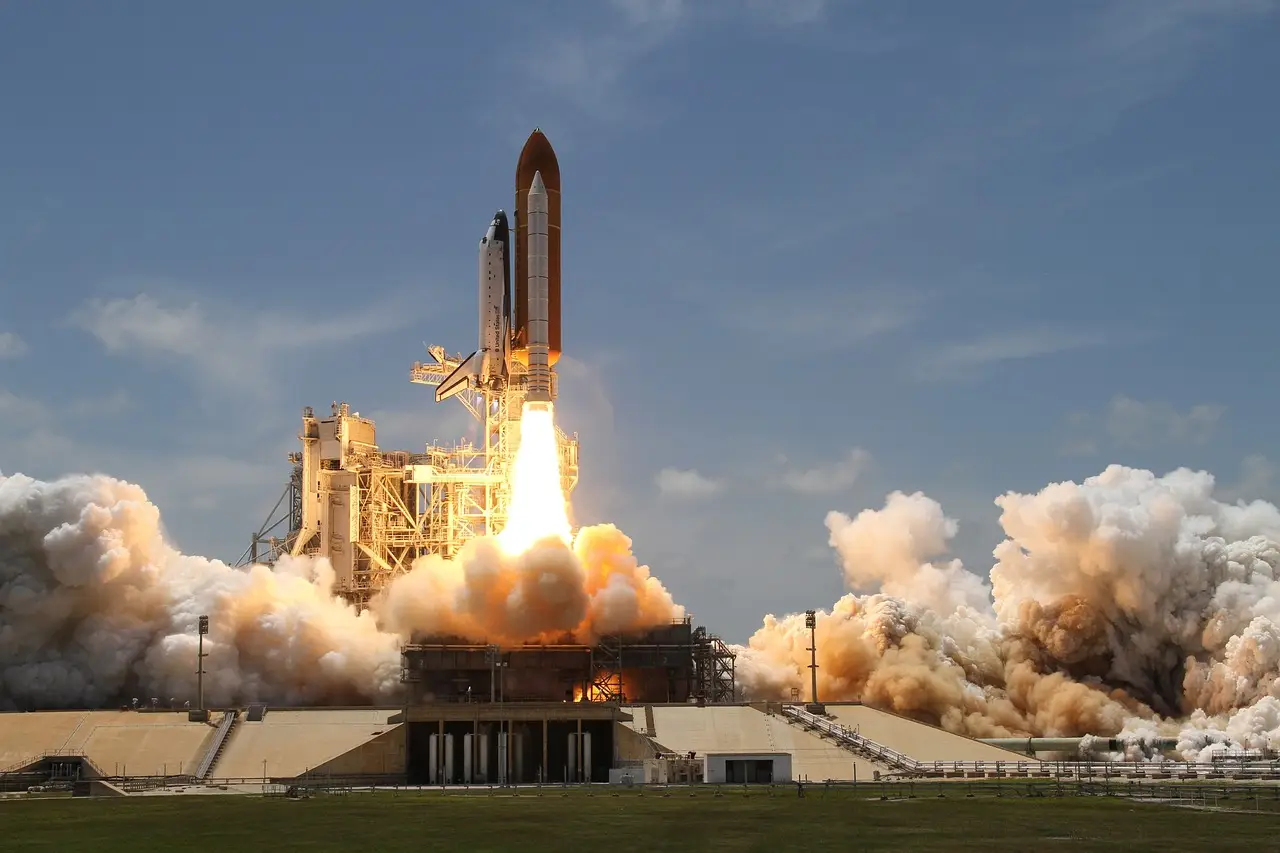
SpaceX went public in June at a $1.77 trillion valuation, the largest offering of any kind in history, raising $75 billion and pushing its market cap above $2 trillion in early trading. Weeks earlier, AI chipmaker Cerebras, a direct challenger to Nvidia, completed a $6.4 billion IPO at a $40.6 billion valuation. Jon Feinberg, Managing Partner and Head of Distribution at ABS Global Investments, argues that by the time most investors can buy these companies, most of the value creation has already happened.
OpenAI and Anthropic have confidentially filed paperwork to go public with the SEC. Anthropic is reportedly in discussions to list shares at a $2 to $3 trillion valuation. Feinberg sees three trends advisors need to understand before the next trillion-dollar IPOs arrive.
Why are companies staying private longer?
The average U.S. company now reaches the IPO market more than 11 years after founding, versus 7.3 years in the late 1990s, excluding biotech. The number of publicly listed U.S. companies has fallen roughly 50% from its peak. Over the same period, the number of venture- and private-equity-backed companies has increased 18-fold.
The private market is where the fastest-growing companies now spend their best-performing years. Among U.S. companies generating more than $100 million in annual revenue, 86% are private — six times the number of public companies. The top 50 private venture-backed companies grow revenue at roughly 150% per year, against about 21% for the top 50 public growth stocks. That is seven times faster.
Anthropic shows how the value stacks up before listing. It raised $65 billion in the second quarter of 2026 at a $965 billion post-money valuation, a 2.37x step-up from its prior round just three months earlier. The move from $380 billion to $965 billion, and now $2 trillion to $3 trillion, occurred two rounds before an IPO, with all the value creation going to private-market investors.
How is late-stage growth equity becoming accessible?
Venture capital has always carried high risk. Series A investing has failure rates between 65% and 75%, with liquidity horizons spanning a decade or more. Late-stage growth equity presents a different profile. A company raising a Series D or later, often one to three years ahead of an IPO, has typically established market leadership, improved margins, and institutional backing. Failure rates in this cohort run closer to 5% to 15%.
The return objective shifts too. The emphasis moves to internal rate of return over a one- to three-year holding period, rather than maximizing the multiple on invested capital over a 10-year horizon. The underwriting starts to resemble how a public equity investor thinks about a position.
Access has changed through registered funds. Historically, this exposure required accredited investor or qualified purchaser status, capital calls, subscription documents, K-1s, and a decade of patience. A registered fund can provide daily pricing, 1099 reporting, more inclusive eligibility rules, and periodic liquidity. The capital can be invested immediately rather than sitting on a five-year commitment schedule.
What does the maturing secondary market change?
Transactions in private secondary shares grew from $26 billion in 2013 to $226 billion in 2025, a nearly ninefold increase. This matters twice over. It gives early investors and employees liquidity without waiting for an IPO, and it lets the market price companies between primary funding rounds.
The secondary market still remains less liquid and less transparent than public markets. Feinberg's advice: advisors should ensure clients understand that liquidity is not guaranteed, and that valuations and holding periods can differ from public-market investments.
What should advisors do before the next wave?
Feinberg points to Cerebras as the template. It was worth $8 billion in the private market two rounds before listing, then IPO'd at $40.6 billion — a roughly 5x step-up. "Increasingly, some of the best investment decisions are made one to three years before the IPO," he writes.
His framework asks several questions: how close is the company to a liquidity event, what is its path to profitability, and which institutional investors are already involved. Advisors should also weigh a client's liquidity needs, investment time horizon, allocation size, and existing exposure to growth companies.
The companies behind the biggest IPOs of 2027 and 2028 may already be known in the private markets, raising capital and trading through secondary transactions. The next wave of IPOs will happen on the public exchanges, but the opportunity to evaluate them starts well before they get there.
Source: GN: Venture Capital
More from Daniel Okafor
Show full bio
Correspondent covering money, funding and market shifts around entrepreneurship, startups and venture funding at Business Bearings.
1,329 articles