U.S. Gold Reserves Worth $1 Trillion; Repricing Could Backfire
U.S. gold reserves hold 261.5 million ounces: $1 trillion at market prices, but $11 billion on the books. Fidelity’s Jurrien Timmer warns repricing could fuel inflation, yields and a weaker dollar.
By Amara Osei
4 min read
What's News
- The U.S. holds about 261.5 million ounces of gold, more than double Germany’s holdings.
- Congress set the official gold price at $42.22 per ounce in 1973 and left it unchanged.
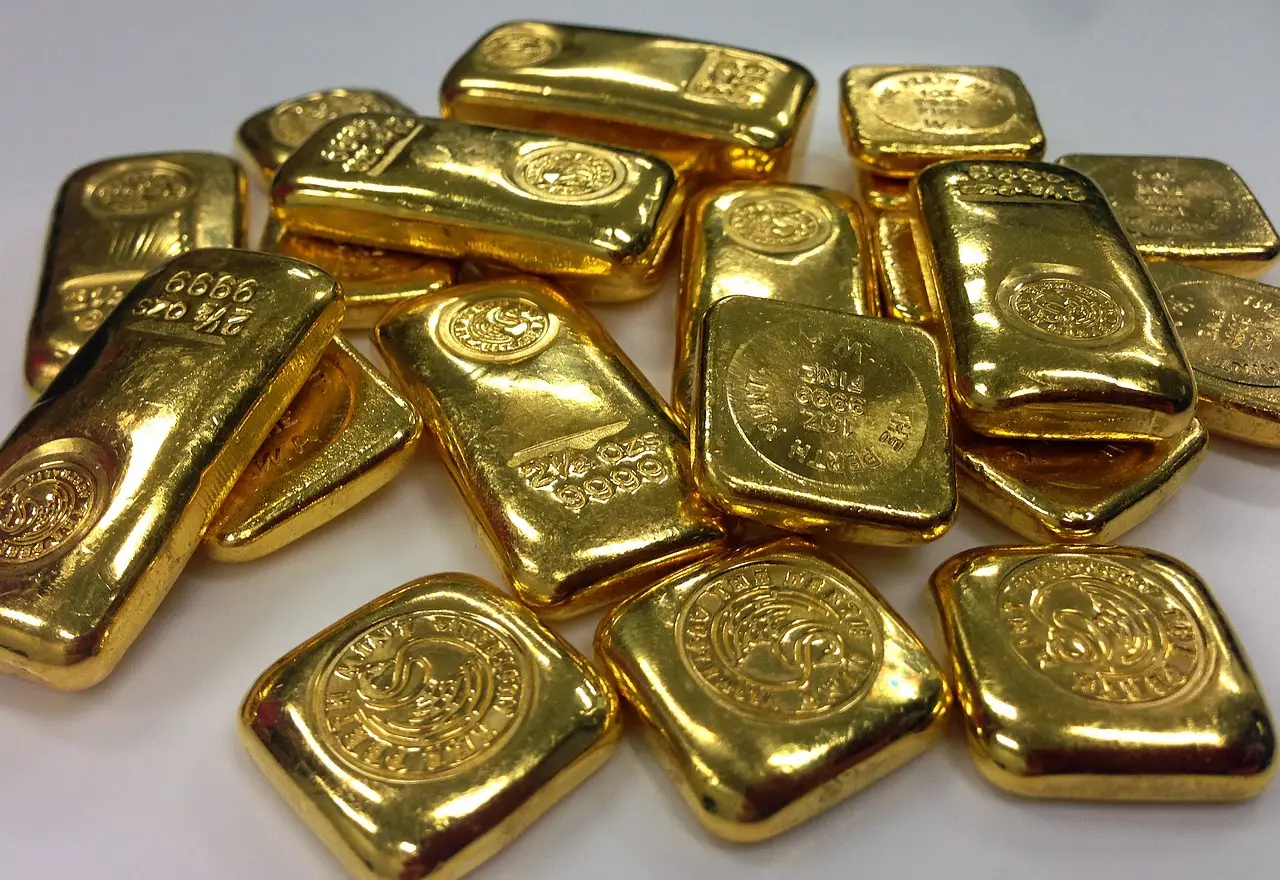
- At about $4,000 per ounce, the U.S. gold reserve would be worth roughly $1 trillion, versus just over $11 billion on the books.
- Gross U.S. debt has reached $40 trillion amid $2 trillion annual deficits and more than $1 trillion in yearly debt-interest costs.
- In July 2026, Treasury Secretary Scott Bessent said Fort Knox’s gold was “present and accounted for” and worth more than $1 trillion at market value.
By Amara Osei
The U.S. Treasury Department’s 261.5 million ounces of gold form the world’s largest reserve, worth about $1 trillion at roughly $4,000 an ounce, but the government books them at just over $11 billion. Congress fixed the official price at $42.22 per ounce in 1973 and has not changed it.
The reserve is more than double Germany’s, the No. 2 holder. That valuation gap has made the metal a recurring target as the United States confronts a $2 trillion federal budget deficit and more than $1 trillion in annual debt-interest costs.
What would repricing change?
The proposal would revalue the gold at market rates. Jurrien Timmer, Fidelity Investments’ director of global macro, said the move could theoretically give the government another $1 trillion to spend without issuing more debt. Repricing would require congressional approval because Congress set the original price.
A recent bill to establish a strategic bitcoin reserve proposed repricing U.S. gold holdings. Comments by Treasury Secretary Scott Bessent last year that the government would monetize the asset side of the U.S. balance sheet and create a sovereign wealth fund fueled speculation that repricing could be included, though the administration later said the idea was not under serious consideration.
President Donald Trump questioned last year whether the gold held at the Fort Knox U.S. Army base was actually there. Treasury’s gold also sits in Denver, the New York Fed, and West Point, New York.
Bessent reignited the gold debate in July 2026. He said the cache was all “present and accounted for,” then added, “the U.S. has the largest pile of gold in the world, over a trillion dollars at current market value.”
Why Timmer expects a backlash
In Friday’s X post, Fidelity’s Jurrien Timmer asked what other tricks Treasury might use to lower funding costs, then examined repricing as a way to free $1 trillion without new debt. “Notwithstanding that an action like this would require congressional approval, my guess is that if the Treasury were attempt do this, it would backfire in a big way,” he wrote.
Timmer expects the U.S. dollar to take a hit because a sudden $1 trillion influx would stoke inflation that is already heating up. He also expects the term premium in Treasury yields to climb even further, pushing up long-term borrowing costs rather than lowering them.
The term premium is the extra return investors demand to cover the risk of holding debt over the long term, and Timmer said it has also climbed. Rates have risen amid expectations for Fed rate hikes, robust economic growth and persistent inflation. Risks investors price can range from geopolitical turmoil to a fiscal crisis or an economic downturn.
What other countries have done
Other governments have revalued gold reserves during the past 30 years, according to a Federal Reserve economist’s August 2025 note. The note listed Germany, Italy, Lebanon, Curacao and St. Maarten, and South Africa. Italy and Curacao and St. Maarten used proceeds through their central banks; South Africa, Lebanon and Germany received the windfall through their central governments.
The note said gold revaluation is not enough to reduce a country’s debt burden. Central governments have often drawn on proceeds to retire existing debt in exceptional fiscal circumstances, but the benefit improves the fiscal position only at the margin and does not resolve larger structural challenges.
Can repricing ease the debt burden?
The Federal Reserve economist framed the limit as scale. Gross U.S. debt has reached $40 trillion, annual budget deficits remain $2 trillion with no end in sight, and debt-interest costs exceed $1 trillion a year. Repricing could create an accounting gain, but it would not remove those structural obligations.
The Treasury Department has already tried less conventional measures, including buybacks of more long-dated debt and intervention to prop up the yen that let Japan avoid selling its Treasuries. Those moves came as Treasury yields reached their highest levels in more than 20 years, adding pressure to interest expense.
Without a plan for the structural deficit, repricing would offer only marginal fiscal relief while risking higher inflation, a weaker dollar and a steeper term premium. Any move by Congress would test whether a roughly $1 trillion accounting gain outweighs the broader market costs.
Original: x.com
More from Amara Osei
Show full bio
Senior reporter covering companies, deals and strategy in entrepreneurship, startups and venture funding at Business Bearings.
1,174 articles