Stand Launches Colorado Homeowners Insurance With Premium Reductions
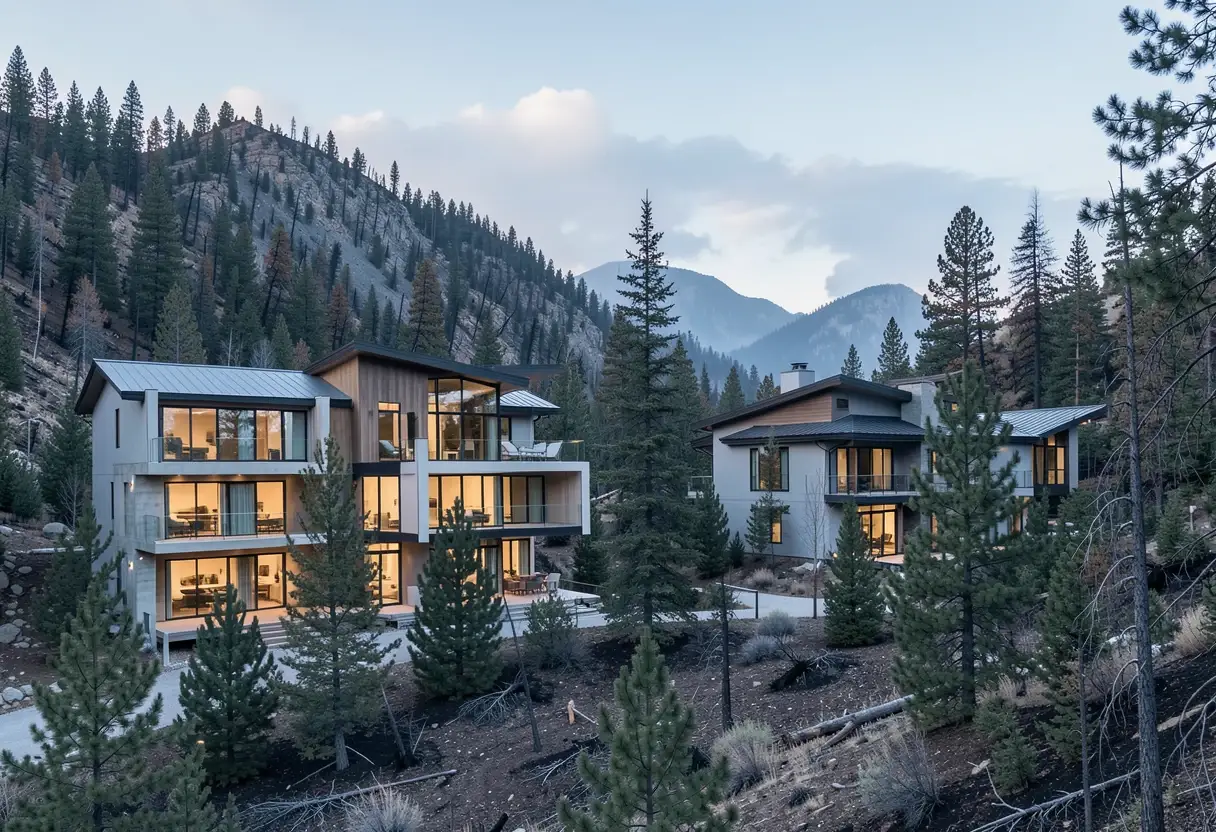
Stand has entered Colorado homeowners insurance, offering premium reductions for wildfire mitigation in mountain communities. Stand reports California premium cuts of up to 60%.
By Nathan Brooks
3 min read
What's News
- Stand announced its Colorado homeowners insurance launch on Tuesday.
- The Colorado launch includes mountain communities with high wildfire risk and premium reductions for mitigation.
- California homeowners who completed recommended wildfire improvements reduced premiums by up to 60%.
- Stand reports more than $10 billion in insured property.
- Concert Specialty Insurance Co., rated A- by AM Best, issues policies in California and Colorado; Stand Insurance Exchange issues Florida policies.
By Nathan Brooks
Stand is bringing homeowners insurance to Colorado, alongside a reported California result: homeowners who completed the company's recommended wildfire improvements reduced their premiums by up to 60%. The company announced the Colorado launch on Tuesday. The offering covers mountain communities with high wildfire risk.
Colorado homeowners can qualify for lower premiums by completing recommended protections. Stand says those measures can include removing trees that could ignite a house and installing screens to protect vents from embers.
Stand first launched in California. The company is now applying its mitigation-linked premium approach in Colorado.
What does this change for Colorado homeowners?
The immediate change is access to premium reductions tied to property work, not just a new policy offering. Stand's announcement does not set one standard discount for every homeowner, and it does not promise Colorado policyholders the same 60% maximum reported in California.
Homeowners should confirm which improvements qualify and what each measure will save before spending money. The California result applies to homeowners who completed recommended improvements. It does not establish an advertised, across-the-board reduction.
Inside the risk model
Stand uses what it calls a “physics-based model” to simulate how a wildfire could reach an individual home. It then identifies measures intended to reduce that risk, linking the physical simulation to the premium reductions available under the Colorado product.
The method moves beyond a general claim that wildfire threatens a region: the company's own description centers on the path a fire could take toward one property. Stand presents the resulting mitigation list as the basis for premium qualification, rather than promising the same saving for every owner or every home.
The announcement names vegetation removal and vent screening as recommended examples. It does not publish a full list of qualifying improvements, installation standards, eligibility rules or expected savings for each measure.
Stand reports more than $10 billion in insured property. That figure measures the property exposure behind the policies; it is not a reported revenue total, customer count or policy count, and the announcement supplies none of those figures.
For Colorado homeowners, the scale matters as context for operational experience, but it does not replace property-specific underwriting. A mountain home's mitigation choices and the model's assessment of how fire could reach it remain central to the premium outcome Stand describes.
Who stands behind the policies
Stand underwrites and services the policies in California and Colorado. Concert Specialty Insurance Co. issues them and carries an A- rating from AM Best.
In Florida, Stand Insurance Exchange issues the policies. The difference matters because policyholders in Colorado deal with policies issued by Concert, while Stand performs the underwriting and servicing work for those policies.
Stand also lists Arch, RenaissanceRe, Hannover, Nephila and Hiscox as its reinsurance partners. Those names define the risk-sharing structure behind Stand's expansion, although the announcement does not disclose the amount, terms or allocation of reinsurance for Colorado.
Those details help buyers identify the policy issuer and risk-sharing counterparties. They do not answer which improvements qualify or how much a Colorado premium will fall, and Stand's announcement leaves those variables open.
The Colorado launch puts Stand's California mitigation evidence into a new market with the risk concentration it has emphasized: mountain communities and individual homes. Homeowners will see whether modeled mitigation can produce durable, property-level savings beyond the company's reported California experience.
For buyers, the immediate value is not merely broader coverage in Colorado's mountain communities. It is a premium mechanism that makes specific mitigation work part of the price. Stand's next disclosures should show which improvements qualify in Colorado and how savings compare with the up-to-60% California benchmark.
Source: insurancejournal.com
More from Nathan Brooks
Show full bio
News editor covering regulation, policy and their impact on entrepreneurship, startups and venture funding at Business Bearings.
2,258 articles